Legal tech can sometimes feel like it’s the whole world. We get absorbed by the details of the technology and are sometimes blinded by big investment announcements, but without the rest of the legal innovation ecosystem around it then this sector-specific software is limited. What do I mean? Let me explain.
What Are We Trying To Achieve?
First, let’s consider what legal tech is actually for. While founders and investors may be excited by the commercial aspect of a software product, for the wider world legal tech only has value if it makes the delivery of legal services achieve the below:
Cheaper – because legal services exist within the broader economy; higher legal and compliance costs act as a tax on business and on wider society as we try to go about our lives or run our companies.
Faster and/or More Efficient – as there is only so much time in a day and if we can get to X outcome faster, then we are better for it as a society. Equally, if we can get to X outcome without expending as much effort or human resources as previously, then this is also a significant improvement. Human society is based upon the principle of limited resources and how to deal with that fact, getting to legal outcomes is as much a part of this as any other aspect of societal need.
Less Risky – all actions carry a degree of risk, from crossing the road to drawing up a contract. If we can reduce the risks inherent in contracting and disputes then we are also doing the world a favour. Less risk can also lead directly to less costs in general, and also connect to forestalling the emergence of future risks.
Greater Knowledge – as one can never know too much about a goal that one is trying to achieve, as that will then help with all of the above, i.e. reduce input costs, human resources required and hopefully reduce risk as well.
Now, it’s fair to say that when it comes to marketing pitches a lot of legal tech is sold as if a lawyer is wandering around the soft-furnishings department of some fancy store and the primary goal is to make the lawyer’s life more comfortable. And that is perhaps a good way to sell your software to the people who pay for it, but if legal tech’s main goal is just to make lawyers’ lives a little bit comfier then that places it on about the same level as selling cushions for your sofa.
Even gaining a foothold in AI’s ever-changing risk landscape requires understanding the collection, storage, processing, and transfer of sensitive data in LLMs and other AI systems.
Data-related risks continue to grow in complexity. Today, companies can customize AI tools using their data to train AI models for specific use cases. However, doing so can introduce new risks and amplify others, such as unauthorized access and data loss. As unknown risks and new laws and regulations arise, GCs will help companies implement best practices for data protection and risk mitigation against data breaches and other types of cyberattacks.
Guide IP, contracts, and licensing agreements.
In-house lawyers may need to identify potential intellectual property issues related to the datasets AI systems ingest and the outputs they generate, including fair use policies and copyright infringement.
Data literacy will help in-house counsel weave narratives out of threads of data. Artwork by Visual Generation / Shutterstock.com
Many in-house lawyers must evaluate vendor agreements that involve data considerations. As organizations collaborate through data sharing or the use of AI systems, GCs will need to review, negotiate, and draft contracts that address data ownership, licensing rights, confidentiality obligations, and liability considerations.
In most instances, data holds value and can be a source of competitive advantage. Data literacy skills are essential to ensure the data AI uses is appropriate, compliant, and not misused. For example, legal work can get complicated when AI uses data from multiple sources, such as public and proprietary databases, which may be subject to differing laws and regulations.
Industry-specific compliance with AI requirements.
Because GCs help shape organizations’ legal strategy and direction, they stay up-to-date with many industry regulations and standards (e.g., HIPAA, FINRA, the SEC, etc.). As business grows increasingly AI- and data-driven, regulations and standards to govern AI systems will arise, particularly for healthcare, finance, and consumer protection.
Lawyers need sharp data literacy skills to assess the legality, ethical implications, and potential risks of using AI systems.
Data literacy elevates compliance from a reactive endeavor to a proactive strategy. Artwork by TarikVision / Shutterstock.com
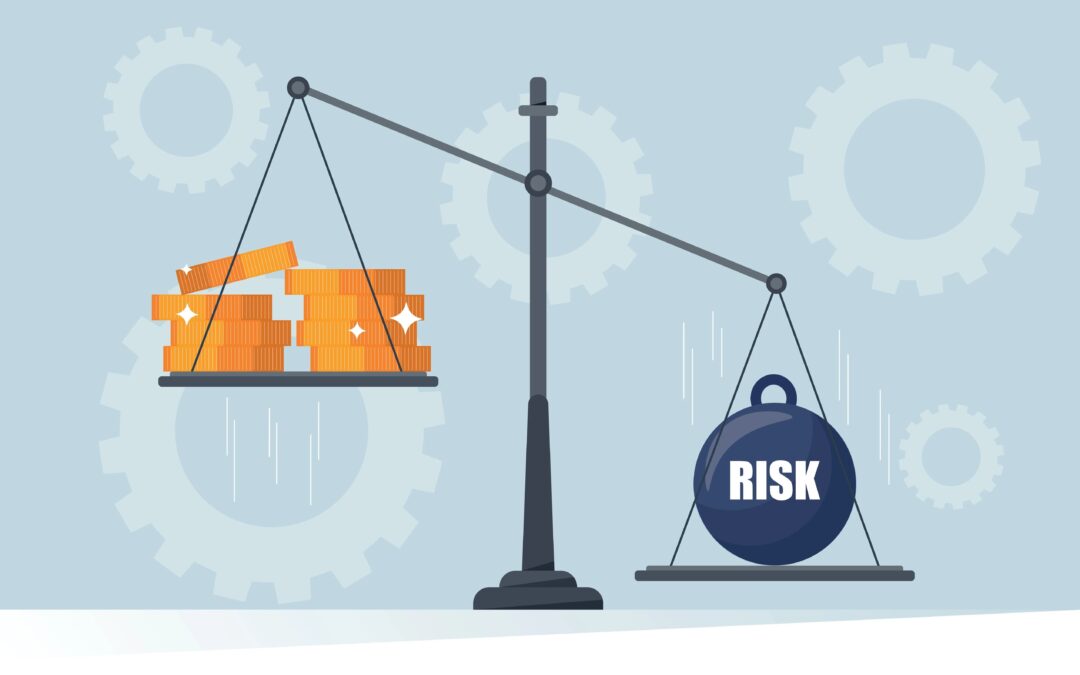
Often, assessing the risks of competing options centers on comparing each one’s expected value — the difference between the odds a course of action will succeed multiplied by the size of the potential gain from its success versus the odds of a negative outcome multiplied by the loss a negative result imposes.
The calculation is easier to describe than perform. One frequent error is miscalculating opportunity benefits and opportunity costs. Getting things right requires accounting for all the benefits of a proposed change, not just the obvious and immediate ones, and identifying the sacrifices and detriments of the status quo.
What stands to be gained…
Consider the decision of whether to routinize the negotiation and legal review of standard, run-the-business contracts. Routinization’s expected value isn’t simply its obvious benefits (e.g., cost savings from outsourcing the work) minus its out-of-pocket costs (e.g., the added expense of hiring an outside managed contracts service provider). It also produces opportunity benefits. These include, for example, faster cycle times for drafting, reviewing, and finalizing contracts, more time for staff to perform higher value work, increased “customer satisfaction” of the law department’s internal clients in the rest of the business, and more.
If the new process includes a mechanism for continuous improvement, then even small, seemingly trivial gains become exponentially larger over time.
The opportunity benefits don’t end there. Aggregated gains may exist, too, whereby the sum of many small gains adds up to a large number — larger still if synergistic gains occur. If the new process includes a mechanism for continuous improvement, then even small, seemingly trivial initial gains become exponentially larger over time. Plus, the project may enable “bootstrapping” other initiatives that bring their own set of benefits.